
SaaS Financial Metrics That Matter: ARR, MRR, CAC, LTV, NRR
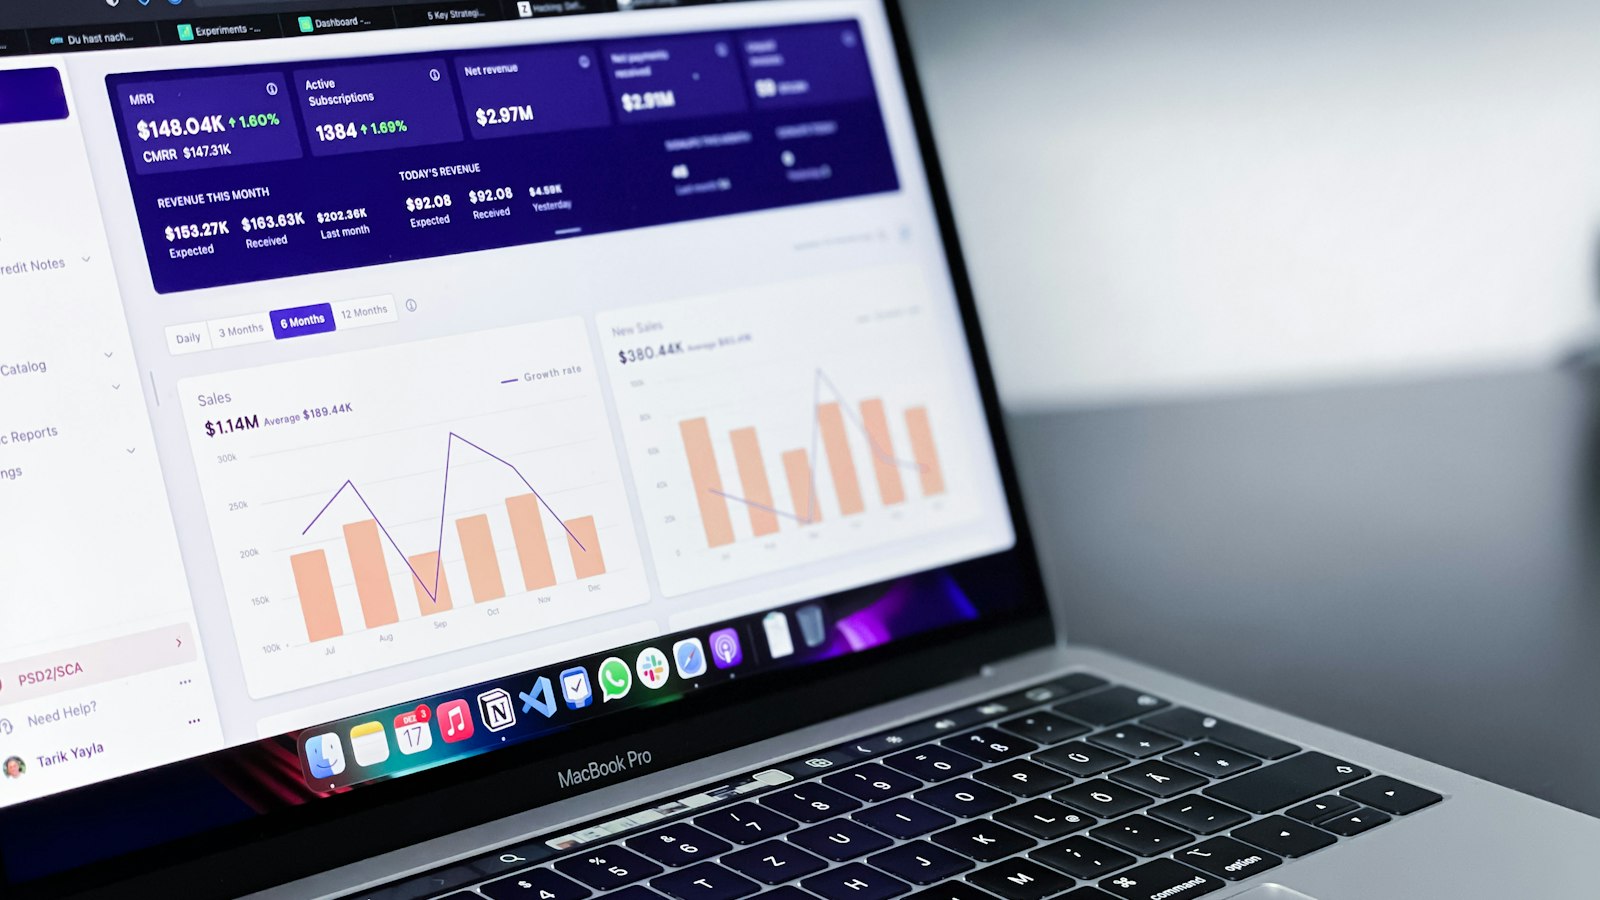
Investors and auditors care most about a handful of SaaS financial metrics that reveal whether a subscription business is growing efficiently and retaining the revenue it generates. The key metrics are Annual Recurring Revenue (ARR), Monthly Recurring Revenue (MRR), Customer Acquisition Cost (CAC), Lifetime Value (LTV), and Net Revenue Retention (NRR). Together, they tell the story of a SaaS company’s unit economics, cash efficiency, and durability, and they carry direct accounting implications under GAAP.
What Are the Core SaaS Financial Metrics?
Before diving into benchmarks and accounting treatment, it helps to understand precisely what each metric measures and how it is calculated.
ARR and MRR: The Revenue Foundation
Monthly Recurring Revenue (MRR) is the total predictable subscription revenue a company generates in a single month from active paying customers. It includes only recurring subscription charges. One-time setup fees, professional services, and usage charges that vary month to month are excluded, because they do not repeat reliably.
Annual Recurring Revenue (ARR) is the annualized view of MRR, typically calculated as MRR multiplied by 12. ARR is the headline figure in investor reporting, annual planning, and M&A due diligence. It serves as the denominator in many efficiency ratios, including ARR growth rate and the Rule of 40.
An important nuance: ARR and MRR are operating metrics, not GAAP revenue figures. A company can have $10 million in ARR and recognize materially different revenue under GAAP depending on when contracts start, how performance obligations are structured, and whether upfront fees are allocated to separate deliverables. Auditors and finance leaders need to understand both numbers and the bridge between them.
CAC: The Cost to Acquire a Customer
Customer Acquisition Cost (CAC) is total sales and marketing spend in a period divided by the number of new customers acquired in that same period. The all-in version includes salaries, commissions, ad spend, marketing tools, events, and agency fees. Every dollar that flows through the sales and marketing function to generate new logos belongs in the calculation.
Blended CAC mixes organic and paid acquisition, which can make efficient performance look worse than it is. More sophisticated finance teams track blended CAC alongside paid CAC separately to understand which channels are actually driving efficiency. Investors increasingly ask for cohort-level CAC data at Series A and beyond, because a blended average can mask deteriorating recent cohorts.
CAC payback period converts the raw CAC figure into a cash recovery timeline: CAC divided by monthly gross profit per customer. Under 12 months is a widely cited benchmark for healthy growth-stage SaaS. Under 6 months is considered excellent. Over 18 months at Series B raises substantive concerns about capital efficiency.
LTV: The Revenue a Customer Generates Over Time
Customer Lifetime Value (LTV) estimates total gross profit generated by a customer over the full relationship. A common formula is: Average Revenue Per Account (ARPA) multiplied by gross margin, divided by monthly churn rate. Because churn rate is in the denominator, even small improvements in retention produce outsized improvements in LTV.
The LTV:CAC ratio is a foundational unit economics benchmark. A ratio of 3:1 is the widely accepted minimum for a viable growth business. Ratios of 4:1 or above are expected at Series A and Series B funding rounds. Ratios below 2:1 suggest the business is spending more to acquire customers than it recovers from them on a risk-adjusted basis.
NRR: The Metric Investors Watch Closest
Net Revenue Retention (NRR), sometimes called net dollar retention (NDR), measures how much of a starting month’s MRR is retained from that same customer cohort at the end of the period, after accounting for churn, downgrades, and expansion revenue from upgrades and cross-sells.
The formula: (Starting MRR minus Churned MRR minus Contraction MRR plus Expansion MRR) divided by Starting MRR, expressed as a percentage.
NRR above 100% means the company grows revenue from its existing customer base even without adding a single new logo. This is what investors mean when they call a SaaS business “self-sustaining.” NRR below 100% means the company must continuously add new customers just to hold its total revenue flat. That condition makes growth expensive and puts downward pressure on valuations.
Why Investors Focus on These Metrics
In 2022, SaaS valuations were driven heavily by growth rate. Since then, the market has repriced around efficiency. Efficiency metrics now appear in a substantial majority of Series A and B term sheets, and the combination of metrics matters as much as any individual number.
NRR Benchmarks by Segment
Current industry data shows meaningful variation in NRR by customer segment (note: these are industry estimates, not codified standards):
- Enterprise (ACV above $100,000): Median NRR near 118%
- Mid-market (ACV $25,000 to $100,000): Median NRR near 108%
- SMB (ACV below $25,000): Median NRR near 97%
The Bessemer Venture Partners framework, widely used in VC due diligence, treats 100% as “good,” 110% as “better,” and 120% or above as “best.” A 10-point improvement in NRR is estimated to translate to a 20 to 30 percent uplift in valuation multiples, based on current market data.
The Rule of 40
The Rule of 40 adds ARR growth rate and operating profit margin. A score at or above 40 indicates a healthy balance between growth and profitability. Companies meeting this threshold command a meaningful valuation premium over peers that do not. The metric is particularly useful because it explicitly allows a growth-stage company to trade profitability for expansion, as long as the combined score clears the threshold.
ARR Growth Rate and Churn
Churn rate benchmarks vary by market segment. Monthly gross revenue churn below 2% is typically acceptable for SMB-focused products. For mid-market and enterprise SaaS, investors expect monthly churn below 1%. Elevated churn is a leading indicator of customer satisfaction problems and erodes both LTV and NRR simultaneously.
The Accounting Side: ASC 606 and SaaS Revenue
Operating metrics like ARR and MRR are not the same as GAAP revenue, and that distinction matters in audits, investor due diligence, and financial reporting. SaaS companies recognize revenue under FASB Accounting Standards Codification Topic 606 (ASC 606), the principles-based revenue recognition standard that replaced the previous rules-based guidance.
Under ASC 606, revenue is recognized when a company satisfies a performance obligation by transferring control of a promised good or service to a customer. For SaaS subscription businesses, the primary performance obligation is typically continuous access to the software platform, which is satisfied ratably over the subscription period. This means a customer paying $12,000 annually upfront generates $1,000 of GAAP revenue each month, with the balance sitting in deferred revenue on the balance sheet.
The Five-Step Model Applied to SaaS
ASC 606 requires companies to work through five steps:
- Identify the contract with the customer.
- Identify performance obligations in the contract. SaaS bundles often contain multiple obligations: software access, implementation services, and ongoing support may each be distinct.
- Determine the transaction price, including variable consideration such as usage-based fees or volume discounts.
- Allocate the transaction price to each performance obligation based on its standalone selling price.
- Recognize revenue as each performance obligation is satisfied.
The allocation step creates complexity in audits. If a SaaS company bundles software access with a paid implementation, the implementation fee cannot simply be recognized at contract signing. It must be allocated based on what each element would sell for independently, then recognized as the relevant obligation is satisfied. Over-combining obligations to simplify accounting and over-separating them to accelerate revenue recognition are both common audit findings.
What Auditors Scrutinize
The AICPA Revenue Recognition Audit and Accounting Guide identifies recurring risk areas in technology and SaaS audits. The deferred revenue schedule is typically the artifact auditors examine most carefully, because it connects GAAP revenue to billings, contract terms, and cash. Material deferred revenue balances that cannot be reconciled to executed contracts are a red flag.
Other common audit findings in SaaS companies include inconsistent treatment of contract modifications, missing documentation for variable consideration estimates, and revenue policies that exist as written documents but are not systematically applied across all customer contracts. Auditors expect a methodology, not just a memo.
For companies preparing for a Series B raise, an acquisition, or their first GAAP-compliant audit, the accounting infrastructure around revenue recognition often requires more investment than the team anticipated. Modus’s audit and assurance practice works with SaaS companies at this stage to establish the controls and documentation that support a clean opinion.
ARR as a Non-GAAP Metric
For public SaaS companies, ARR is generally treated as an operating metric rather than a non-GAAP financial measure, but SEC disclosure expectations still apply. The SEC’s guidance on key performance indicators (Release 33-10751) requires that disclosed metrics be clearly defined, consistently applied, and not misleading. ARR definitions vary across companies. Some use contracted ARR, others use run-rate MRR, and others use a hybrid, so investors and auditors look for explicit definitions in financial statements and offering documents.
Private companies are not subject to SEC reporting requirements, but PE sponsors and VC investors routinely impose definition consistency as a condition of continued investment. A company that restates its ARR figure during due diligence due to definitional inconsistency faces serious credibility issues regardless of the underlying business performance.
Building the Metrics Infrastructure
Strong SaaS financial metrics are not just reporting outputs. They require underlying systems: a subscription billing platform that tracks contract start dates and modifications, a CRM that captures deal economics at the line level, and a revenue recognition system that automates ASC 606 compliance and maintains the audit trail auditors need.
Finance leaders at growth-stage SaaS companies often operate on spreadsheets far longer than is advisable. The first audit, fundraising round, or acquisition process typically surfaces gaps: ARR tracked in one spreadsheet, deferred revenue in another, with no automated reconciliation. Building the bridge between operational metrics and GAAP financials is a core priority for any SaaS company approaching $5 million in ARR or contemplating outside capital.
Modus’s advisory practice supports SaaS finance teams in designing the reporting architecture that serves both investor-facing metrics and auditor-facing accounting documentation.
Frequently Asked Questions
What is the difference between ARR and GAAP revenue for a SaaS company?
ARR is an operating metric that represents annualized contracted recurring revenue, typically calculated as MRR multiplied by 12. GAAP revenue is recognized under ASC 606 as performance obligations are satisfied, usually ratably over the subscription period. A company can have $10 million in ARR and recognize less GAAP revenue in a given year if a portion of contracts were signed late in the year and deferred revenue remains on the balance sheet.
What NRR is considered healthy for a SaaS company?
Current industry benchmarks treat 100% NRR as the minimum threshold for a stable business, 110% as strong, and 120% or above as best-in-class. Enterprise-focused SaaS companies typically achieve higher NRR than SMB-focused businesses because enterprise customers are harder to acquire and have lower baseline churn rates. These thresholds are industry estimates, not codified standards.
How do auditors evaluate SaaS revenue recognition?
Auditors apply the ASC 606 five-step model to the company’s subscription contracts, looking specifically at whether performance obligations are correctly identified and separated, whether the transaction price is properly allocated to each obligation based on standalone selling price, and whether revenue is recognized in the correct period. The deferred revenue schedule, contract modifications, and variable consideration documentation receive the most scrutiny.
What is CAC payback period and why does it matter?
CAC payback period is the number of months required to recover the cost of acquiring a customer through gross profit generated by that customer. It is calculated as CAC divided by monthly gross profit per customer. A payback period under 12 months is generally considered healthy for growth-stage SaaS. Payback periods over 18 months suggest the business is consuming capital faster than it recovers acquisition costs, which constrains growth and reduces runway.
Is ARR a non-GAAP measure subject to SEC rules?
For public companies, ARR is generally treated as an operating metric (a KPI) rather than a non-GAAP financial measure, but the SEC’s guidance under Release 33-10751 still requires that it be clearly defined, consistently calculated, and not misleading. ARR definitions vary across companies, so public filers typically define the metric explicitly in their 10-K or earnings releases. Private companies are not subject to SEC reporting, but investors and acquirers impose similar consistency expectations in due diligence.
What does net revenue retention above 100% mean for valuation?
When NRR exceeds 100%, a SaaS company grows revenue from its existing customer base without adding any new customers. This compounding dynamic means the business requires less capital to sustain growth, which investors reward with higher revenue multiples. Industry data suggests a 10-point improvement in NRR translates to a 20 to 30 percent increase in valuation multiples, though the relationship varies by stage and sector. These are market estimates, not guaranteed outcomes.
Filed under: Industry Accounting Technology & SaaS